
Critical Audit Matters PCAOB: What They Are and Why They Matter
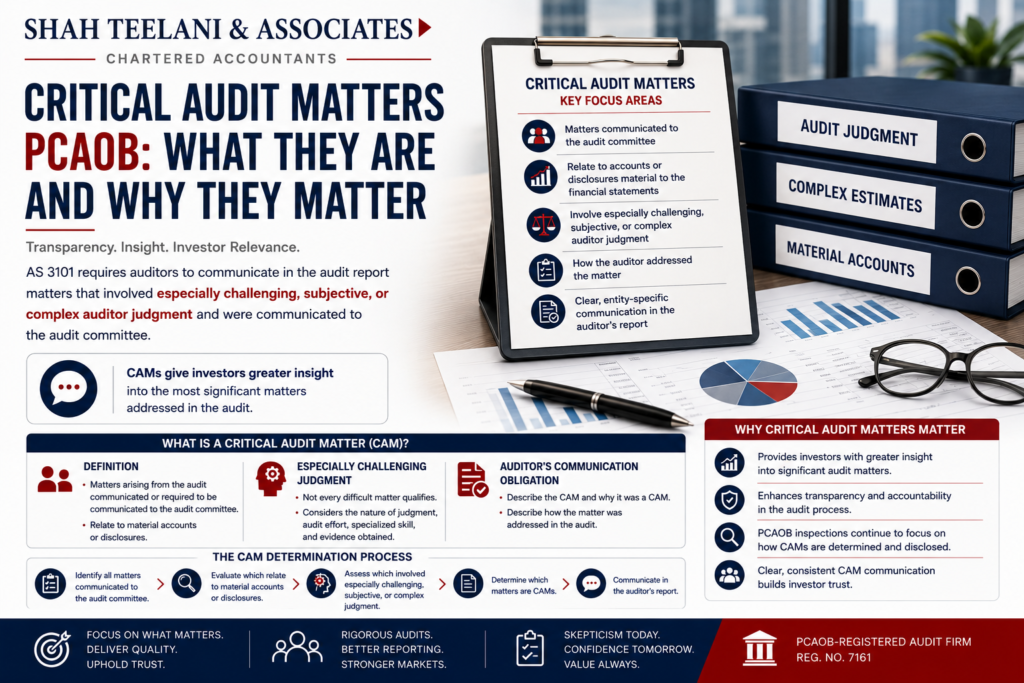
Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Critical audit matters PCAOB requirements introduced under AS 3101 represent the most significant change to the auditor’s report in decades. Before AS 3101, auditor reports followed a standard template. Investors received an opinion — but little insight into the challenges auditors […]
Going Concern PCAOB Audit: The Auditor’s Responsibility Under AS 2415
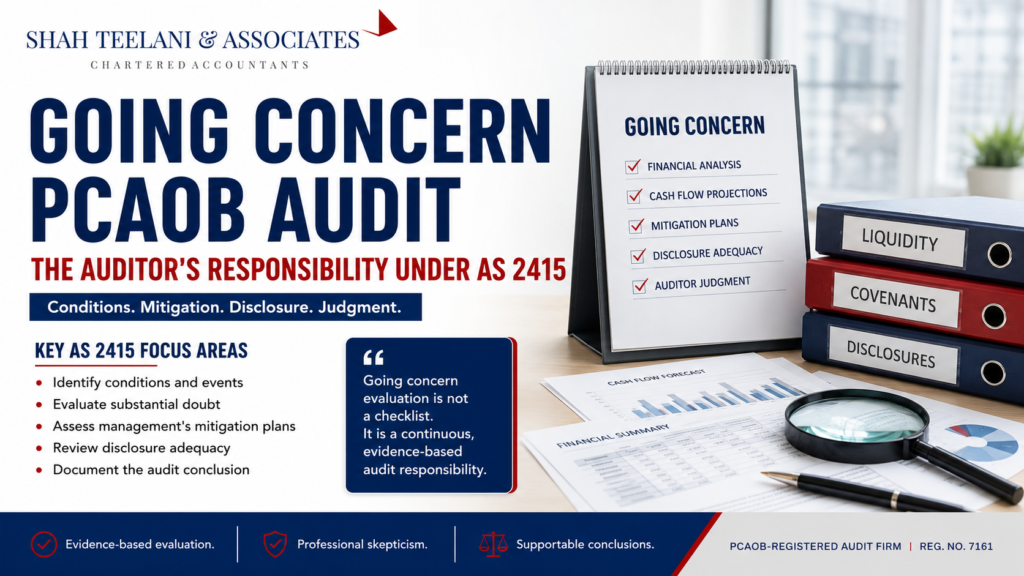
Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Going concern PCAOB audit responsibilities sit at the intersection of financial reporting, risk assessment, and investor protection. Every auditor must evaluate whether substantial doubt exists about a company’s ability to continue operating. Few areas carry higher stakes — for investors, for […]
Related Party Transactions Audit: What PCAOB AS 2410 Requires
Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Related party transactions audit procedures rank among the most scrutinized areas in PCAOB inspections. Nearly every major financial reporting fraud in modern history involved related party transactions that auditors failed to identify or adequately challenge. Enron’s transactions with special purpose entities, […]
Revenue Recognition Under PCAOB Scrutiny: What Auditors and Issuers Must Know

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Revenue recognition PCAOB inspectors examine ranks as the single most consistently deficient area across all inspection cycles and all firm categories. Year after year, inspection reports from Big Four firms, mid-tier firms, and smaller registered firms all identify revenue testing as […]
Journal Entry Testing PCAOB: Why Inspectors Focus Here

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Journal entry testing PCAOB inspectors evaluate ranks among the most persistently deficient areas across every category of registered firm. The PCAOB published a dedicated Audit Focus publication on journal entries in January 2025 — specifically because staff continued identifying a large […]
Professional Skepticism in PCAOB Audits: What It Actually Requires in Practice

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Professional skepticism PCAOB auditors must apply is one of the most cited requirements in auditing standards — and one of the most consistently misapplied in practice. Every auditor understands the phrase. Far fewer apply it in the way PCAOB inspectors expect […]
Audit of Estimates and Complex Accounting Areas: What PCAOB Standards Require

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Auditing accounting estimates consistently ranks among the top deficiency areas in PCAOB inspection reports. Nearly every set of public company financial statements contains estimates — goodwill impairment, allowance for credit losses, fair value measurements, revenue recognition under complex arrangements, contingent liabilities, […]
Audit Sampling Techniques for Modern Auditors: What PCAOB Standards Require

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Audit sampling techniques form the operational backbone of every public company engagement. Testing every transaction in a large population is rarely feasible under real-world time and resource constraints. Consequently, auditors must select samples that provide a reasonable basis for drawing defensible […]
Audit Evidence: The Quality vs Quantity Debate Under PCAOB Standards

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Audit evidence quality sits at the center of the most persistent deficiency pattern in PCAOB inspection history. Engagement teams filled files with documentation. Yet the audit opinions still lacked adequate support — because the evidence was insufficient, unreliable, or unresponsive to […]
Key Components of a Strong Audit Documentation Process Under PCAOB Standards

Published by Shah Teelani & Associates | PCAOB-Registered Audit Firm | Reg. No. 7161 Building a strong audit documentation process requires discipline from day one — not a cleanup sprint at the end of fieldwork. Engagement teams must embed documentation into every procedure, every supervisory review, and every evidence step throughout the entire engagement lifecycle. […]
